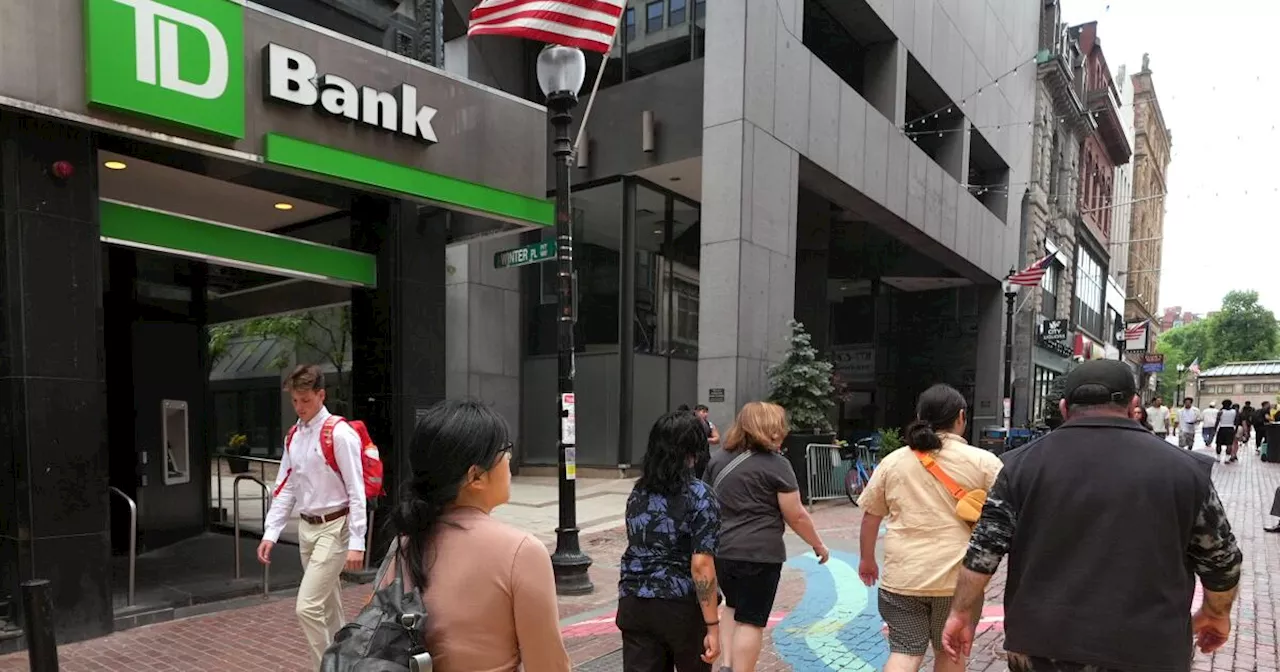
The Trump administration is directing banking regulators to discourage undocumented immigrants from accessing financial services.. This effort utilizes a combination of risk-based guidance and tax policy changes to create barriers for those without legal work authorization.
The OCC, FDIC, and NCUA's new KYC guidance
Three major regulators—the Office of the Comptroller of the Currency (OCC), the Federal Deposit Insurance Corporation (FDIC), and the National Credit Union Administration (NCUA)—are issuing new guidance centered on "Know Your Customer" (KYC) obligations. According to the report, this guidance specifically targets financial institutions that provide services to borrowers who are unauthorized to work in the United States.
The Trump administration is framing the presence of undocumented immigrants in the banking system as a threat to financial stability. The regulators argue that individuals living in the U.S. illegally represent a heightened credit risk because they may be unable to repay loans if they are deported from the country.
The May executive order and FinCEN's fraud alerts
This regulatory pressure stems from a May executive order issued by President Trump, which demanded that banks and financial firms implement closer scrutiny of the citizenship status of their customers. The goal of this order is to detect and prevent undocumented immigrants from opening new accounts, securing credit cards, or obtaining loans.
Adding to this scrutiny, the Financial Crimes Enforcement Network (FinCEN) issued an alert in May regarding money laundering, payroll tax fraud, and identity theft. As the report notes , FinCEN urged banks to monitor for more than a dozen "red flags" that might indicate a customer is an unauthorized worekr, further linking undocumented status with criminal financial activity.
Treasury's November shift on refundable tax credits
The administration's strategy extends into the tax code to further isolate undocumented residents. In November, the Treasury Department announced a reclassification of certain refundble tax credits, labeling them as federal public benefits. This change effectively makes some immigrant taxpayers ineligible for these credits, regardless of whether they have filed returns and paid taxes.
Tax experts have pointed out that this Treasury Department policy specifically impacts vulnerale groups, including those with Temporary Protected Status and immigrants who arrived as children under the Deferred Action for Childhood Arrivals (DACA) program. By removing these financial incentives, the administration is creating a tangible economic penalty for undocumented status.
The missing data on undocumented bank account holders
A significant gap remains in the administration's approach: there is currently limited data on exactly how many undocumented immigrants hold bank accounts or loans in the United States. Because these figures are not publicly quantified, the actual practical impact of the OCC, FDIC, and NCUA guidance remains uncertain.
Furthermore, the report highlights a critical concern that these measures may not actually eliminate the presence of undocumented immigrants in the economy, but rather push them toward unregulated financial channels. This shift could increase the vulnerability of immigrant communities to exploitation and fraud by moving them away from the protections of the formal U.S. financial system.
A shift toward economic barriers beyond deportation
These measures signal a broader evolution in the Trump administration's immigration enforcement agenda. Rather than relying solely on the physical threat of deportation, the administration is now implementing a system of "financial deportation," where the inability to access basic banking and tax benefits serves as a primary deterrent.
This trend mirrors a wider effort to integrate immigration enforcement into the everyday economic lives of residents. by utilizing regulatory guidance rather than direct mandates, the White House is incentivizing banks to voluntarily distance themselves from undocumented customers to avoid perceived risks to their own stability.
Comments 0