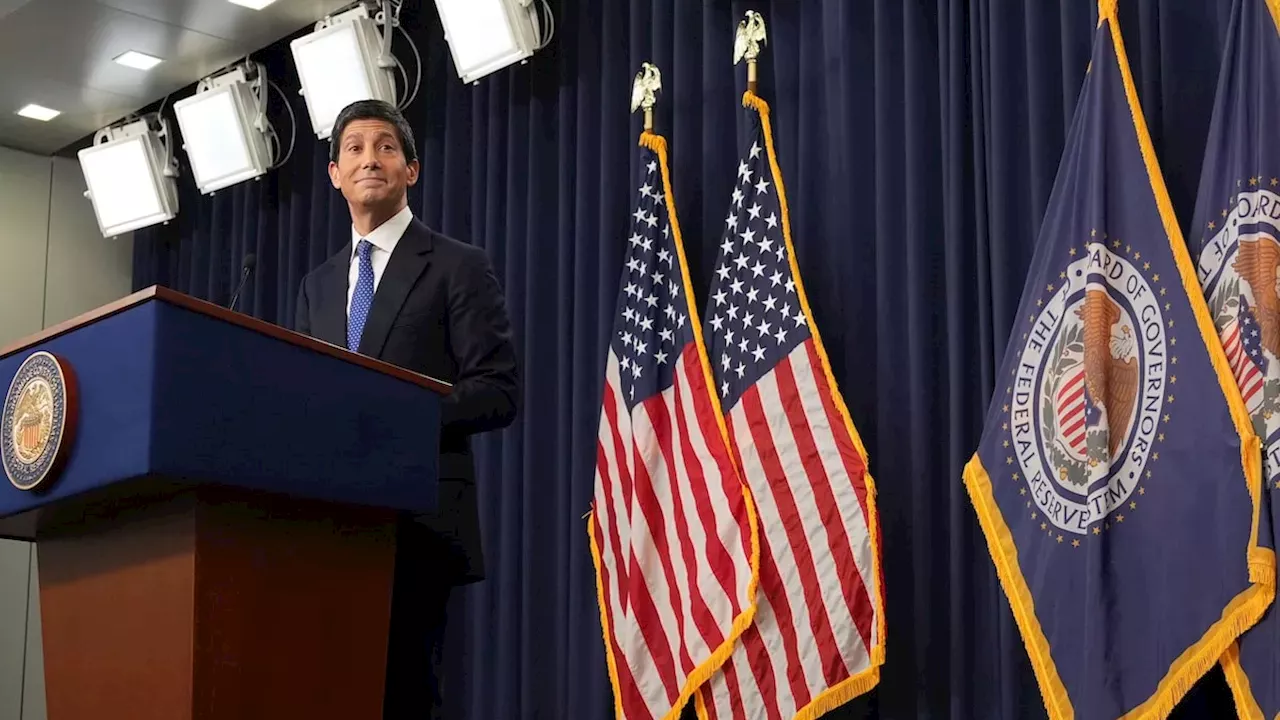
Global bond yields are surging in the US, UK, and Japan as investors grow skeptical of government debt levels. This synchronized volatility is undermining traditional investment strategies and forcing central banks into a hawkish stance to avoid repeating past inflationary errors.
The 2022 Repeat: Why Balanced Portfolios are Failing Again
The current volatility in the global bond market is mirroring the turmoil of 2022, where the traditional "balanced portfolio"—designed to use fixed-income assets as a hedge against equity losses—collapsed. Because bond prices move inversely to yields, the rapid ascent in rates has caused simultaneous declines in both stocks and bonds, leaving investors without their usual safety net.
According to David MacNicol of MacNicol and Associates Asset Management, this trend is not merely a local issue but a systemic reassessment of global debt levels and the persistence of inflation. This shift is being amplified by a volatile geopolitical landscape and intensifying trade disputes, which have eroded the perceived stability of sovereign debt.
From 5.6% US Treasuries to 6% British Gilts
The scale of the sell-off is evident in the surge of long-duration government yields to levels not seen in decades. As reported, the United States 10-year treasury yield has climbed above 5.6 percent, while the British 30-year yield has exceeded 6 percent. Even Japan, long known for its ultra-low rate environment, has seen its 10-year yield approach 3 percent.
These figures suggest a fundamental erosion of confidence in the global fiscal framework. Central banks are now trapped in a precarious balancing act, attempting to curb stubborn inflation without triggering a severe economic contraction. Many policymakers are operating under a cloud of past failure, terrified of repeating the pandemic-era mistake of reacting too slowly to inflationary pressures.
The $6 Billion Buyback and the Scott Bessent Controversy
In an attempt to stabilize the market, the United States Treasury recently tripled its bond buyback program, increasing the amount from 2 billion to 6 billion dollars. While the U.S. Treasury officially stated the move was intended to enhance market liquidity, many investors view the intervention as a thinly veiled attempt to artificially suppress interest rates and lower borrowing costs for the government.
This maneuver has sparked significant political and professional backlash. Treasury Secretary Scott Bessent faced criticism for intervening in the markets just weeks before the U.S. midterm elections, a period when the electorate is particularly sensitive to borrowing costs. Despite the multi-billion dollar injection , the report says the move failed to lower interest rates and instead pushed long-term rates higher, fueling skepticism regarding the Treasury's motives.
Will Stanley Druckenmiller's Warning of Wasted Capital Come True?
The tension between economic fundamentals and government intervention has drawn a sharp warning from Stanley Druckenmiller, a former mentor to Scott Bessent. Druckenmiller, famous for his historic short of the British pound, argued that governments attempting to defend prices against economic fundamentals are destined to lose, questioning how much capital will be wasted before the U.S. government finally concedes.
This raises a critical , unanswered question: at what point does the Federal Reserve's hawkishness become counterproductive? While the source details the pressure on national currencies and the struggle of global central banks to protect purchasing power, it rmeains unclear if there is a viable exit strategy that avoids a global recession. furthermore, the report focuses heavily on the U.S. and Japan,leaving the specific internal fiscal responses of European nations largely unexamined.
Comments 0