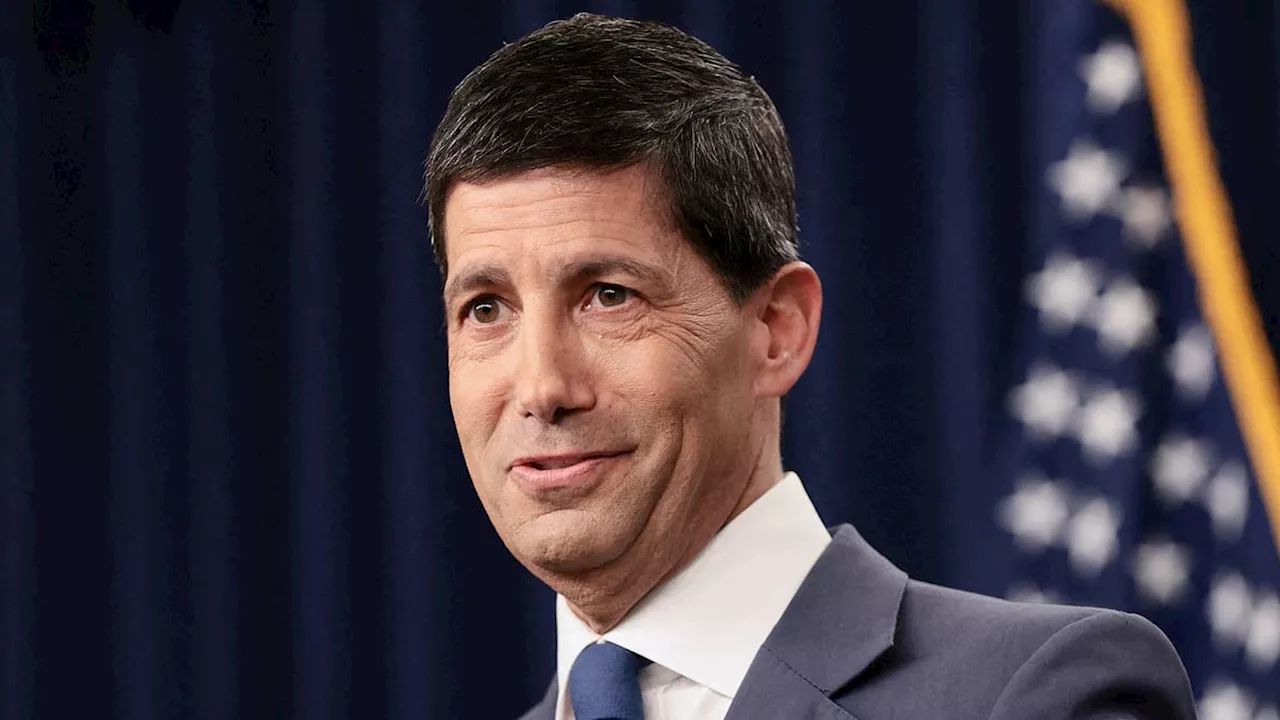
The US Federal Reserve is expected to maintain interest rates between 3.5% and 3.75% during its next meeting. This decision,led by new chairman Kevin Warsh, follows a slight decline in inflation and avoids a public confrontation with President Donald Trump.
The 3.5% to 3.75% range and the Trump truce
The US Federal Reserve is likely to keep interest rates within the 3.5% to 3.75% range next month, a move that effectively signals a temporary truce with the executive branch. According to the report, President Donald Trump has consistently advocated for lower rates since taking office, creating a high-pressure environment for the central bank's leadership.
By opting for stability rather than a hike, new Federal Reserve Chairman Kevin Warsh avoids a direct political clash. This positioning allows the US Federal Reserve to maintain its operational autonomy while simultaneously satisfying the White House's preference for a more accommodative monetary policy.
A 3.4% inflation dip and the 2% target gap
Recent economic data indicates that US consumer prrices climbed 3.4% in the year ending in July, marking a slight decrease from the 3.5% recorded the previous month. While this cooling trend eases the immediate pressure to raise borrowing costs, the US Federal Reserve is still operating well above its long-term inflation target of 2%.
Scott Anderson, the chief US economist at BMO Capital Markets, suggests that this latest data should reduce the US Federal Reserve's concerns regarding an energy-driven inflation spiral. However, as the report notes, the central bank remains wary of the gap between current price levels and the 2% goal, meaning the threat of future hikes has not been entirely eliminated.
July job losses and Middle East oil shocks
The decision to hold rates is not based on inflation alone ; the US Federal Reserve is also weighing surprise job losses that occurred in July. This labor market volatility, combined with the cooling inflation figures, provides Chairman Kevin Warsh with the justification needed to pause rate increases.
Additionally, the US Federal Reserve has observed that the oil price shock triggered by the Middle East conflict has had limited effects on the broader economy thus far. Matt Cornwell, a portfolio manager at Nedgroup Investments, notes that the absence of "nasty surprises" allows Kevin Warsh to maintain a cautious, wait-and-see bias in his policy approach.
The missing evidence on core services inflation
Despite the current pause, a critical piece of the puzzle remains missing: definitive proof that core services inflation is moderating. Scott Anderson of BMO Capital Markets argues that the US Federal Reserve will require more evidence of a solwdown in this specific sector before the possibility of a rate hike is completely removed from the table.
This leaves an open question regarding the Fed's long-term trajectory. While the current data supports a hold , it remains unclear if the US Federal Reserve is merely delaying an inevitable hike or if the cooling trend in July represents a permanent shift in the economic landscape.
Comments 0