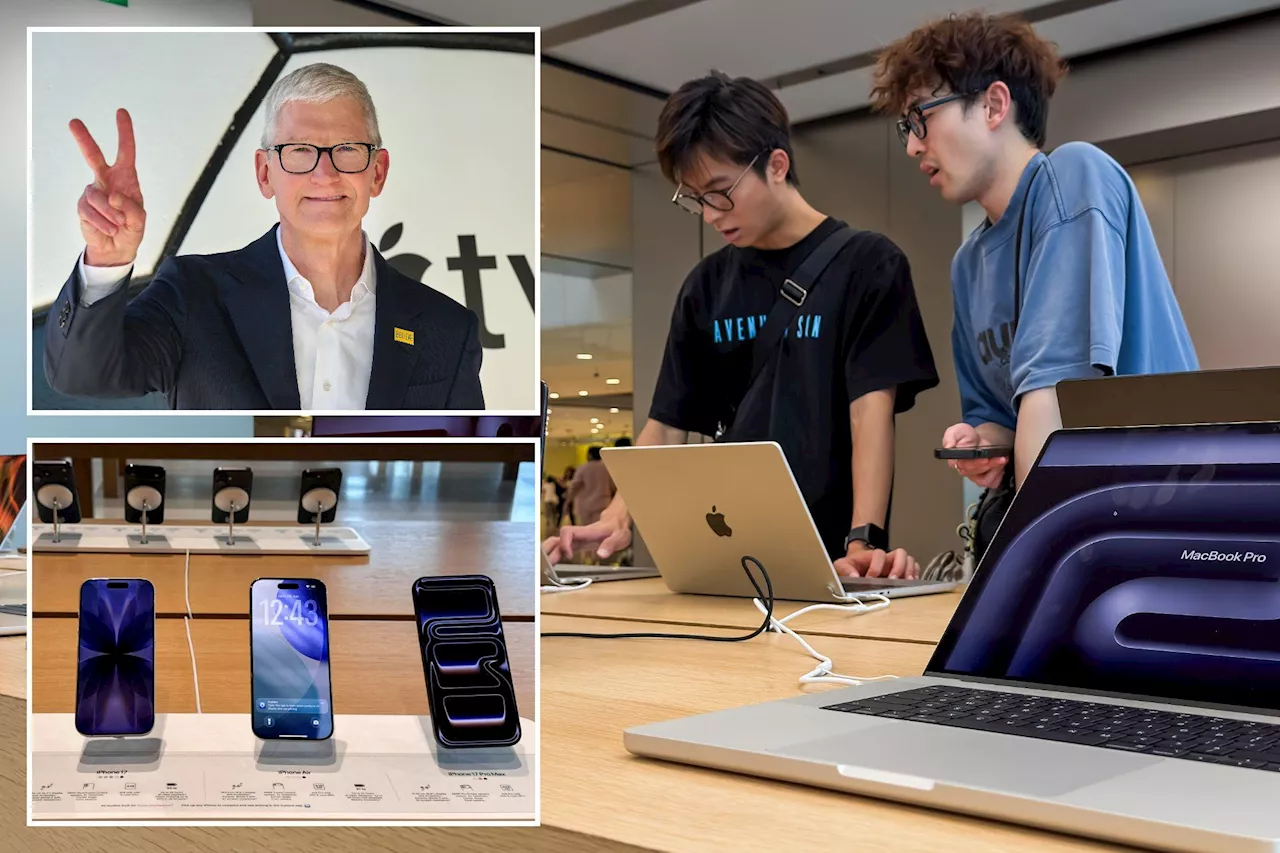
Apple's stock tumbled 6% in after-hours trading following a revenue forecast for the September quarter that lagged behind analyst expectations. Despite reporting strong fiscal third-quarter results, the company warned of ongoing supply constraints affecting its hardware delivery.
The 9% to 11% growth forecast that spooked Wall Street
While Apple reported a strong fiscal third quarter ending June 27, the market reacted sharply to the outlook for the current period. Chief Financial Officer Kevan Parekh informed investors that Apple expects revenue growth between 9% and 11% for the quarter ending in September. According to LSEG data, this projection falls short of the 12% increase that Wall Street analysts had predicted.
This cautious guidance comes despite a robust performance in the previous quarter, where Apple saw sales rise 16.4% to $109.42 billion. The company managed to beat overall profit estimates, partly aided by price increases across its consumer electronics lineup and specific tariff refunds that boosted gross margins to 50.1%.
Apple Silicon shortages and the friction with Micron MU
The primary drag on Apple's growth is a systemic struggle to secure essential components.. CEO Tim Cook told Reuters that an industry-wide shortage of advanced chipmaking technology has limited the production of Apple Silicon chips. This supply chain rigidity has made it difficult for Apple to meet high demand, particularly for its Mac lineup, which grew 29% thanks to the MacBook Neo and MacBook Pro.
As reported, this struggle is compounded by a "thinly concealed conflict" with memory supplier Micron MU. The tension stems from a global crunch in memory chip supplies, exacerbated by the massive spending of other Big Tech firms to build AI data centers. While Apple has been more conservative with its own data center investments compared to Alphabet's Google, it is still feeling the ripple effects of the AI arms race in the hardware market.
Record $54.25 billion iPhone sales vs. sliding iPad revenue
The company's hardware performance remains a mixed bag of record-breaking highs and surprising dips. iPhone sales reached $54.25 billion,a 21.7% increase that represents the best third-quarter performance in the product's history. This surge occurred even as customers typically slow their spending in anticipation of new fall releases.
Conversely, the iPad continues to struggle, with sales falling 5.9% to $6.19 billion, missing LSEG analyst expectations of $6.92 billion. Tim Cook attributed this decline to a "tough compare" against the previous year's launch of the budget-friendly A16 iPad. additionally, the services division—which encompasses iCloud and the App Store—missed estimates by reporting $30.74 billion in revenue, a 12.1% increase.
Ending the cash-return goal to fund AI infrastructure
Apple is signaling a strategic pivot in how it manages its balance sheet to stay competitive in the AI era. The company has ended its long-standing commitment to return all of its cash to shareholders, suggesting that upcoming capital needs may take priority. This shift coincides with the launch of a revamped Siri virtual assistant, developed with help from Google, which emphasizes on-device AI tasks for Mac users to avoid monthly subscription fees.
This move reflects a broader trend where hardware giants must balance shareholder dividends with the staggering costs of AI integration. By prioritizing on-device processing, Apple is attempting to differentiate itself from the cloud-heavy strategies of its rivals, though this approach relies heavily on the very chip supplies that are currently in short supply.
Will September bring the expected iPhone price hikes?
One critical uncertainty remains regarding how Apple will maintain its margins amidst rising memory costs. While the report notes that analysts increasingly expect Apple to raise iPhone prices around its September launch event, the company has not officially confirmed this move. It remains unclear if price hikes will be sufficient to offset the supply chain pressures described by Tim Cook.
Furthermore, the report focuses heavily on Apple's internal projections and LSEG data, leaving a gap in perspective from the suppliers themselves.. It is yet to be seen how Micron MU or Taiwan Semiconductor Manufacturing Co. plan to resolve the bottlenecks that are currently capping Apple's revenue potential.
Comments 0